

Articles and Updates
September 2026
September Webinar Key Takeaways: Weighing the Trade-Offs of Buying and Selling Options
In September, OIC instructor Mark Benzaquen led two companion webinars: Buying Options: Key Considerations for Investors and Selling Options: Key Considerations for Investors. Both sessions covered the same core mechanics — pricing, the Greeks, volatility, strike and expiration selection, and position management — from opposite sides of the contract. A buyer pays a premium for defined risk and open-ended reward, while a seller collects a premium for defined reward and risk that can be substantial or unlimited. That basic asymmetry runs through every topic the two sessions shared, from how time and volatility move against a buyer and for a seller, to how strike and expiration choices trade cost against probability of profit or assignment.
What We Covered:
Premium, Decay and the Greeks: Friend to One Side, Foe to the Other
- An option's premium if it's in-the-money combines intrinsic value, what an investor would capture by exercising now, and extrinsic value, which reflects time, interest rates, dividends and implied volatility. Intrinsic value doesn't erode on its own, but extrinsic value shrinks daily and shrinks faster as expiration nears. At-the-money and out-of-the-money options have no intrinsic value and are comprised of just extrinsic value.
- Theta, which measures time decay, and Vega, which measures sensitivity to implied volatility, tend to move together against a buyer when a stock trades quietly. A buyer needs the stock to move favorably or implied volatility to rise to offset the premium paid and/or the erosion of value from time decay; a seller benefits when neither happens.
- Delta and Gamma describe how sensitive a position is to the stock's price and grow more sensitive near expiration. Sellers generally want a contract to finish at or out of the money, with no intrinsic value left, while buyers want the reverse outcome.
Volatility and Corporate Events: Pricing the Unknown
- Implied volatility often climbs ahead of a scheduled event, such as an earnings release, then drops sharply once the outcome is known, a pattern known as volatility crush. A buyer who pays a high premium right before the announcement can still lose money if that drop offsets the stock's gain.
- Comparing today's implied volatility with its own history, using IV rank and IV percentile, helps investors judge whether a premium is expensive or cheap relative to itself, not to some other contract.
- Dividends and other corporate actions, including stock splits and mergers, affect pricing on both sides of a trade. Dividends tend to reduce call values and increase put values, and a seller holding a short call through the ex-dividend date takes on the real risk of early assignment.
Strike, Expiration and Liquidity: The Cost of Getting In and Out
- For buyers, moving from an out-of-the-money strike to an in-the-money strike raises both the cost and the dollar risk of a contract while lowering the breakeven move needed. For sellers, a strike closer to the stock price raises the premium collected along with the odds of assignment.
- Sellers should weigh yield, not premium alone: a modest premium against a large amount of tied-up collateral produces a low annualized return even in a winning trade. Expiration carries a similar trade-off — weekly options cost less but leave less time to work, while LEAPS cost more because sellers demand payment for the added time and uncertainty.
- The bid-ask spread matters in percentage terms, not just dollars, and trading volume plus open interest signal how much competition exists at a given strike. Wide spreads aren't necessarily a red flag; some securities trade that way, and investors can place an order between the posted bid and ask.
Position Management and the Trade Life Cycle
- Most contracts don't run to expiration. Roughly 72% are closed out early through a buy-to-close or sell-to-close order, about 20% expire worthless, and only 6% to 8% are actually exercised or assigned.
- Rolling a position — closing the current contract and opening a new one at a different strike, a later expiration, or both — lets an investor buy more time for a thesis or adjust to new expectations. It's a brand-new trade, though, with its own spread, Greeks and added commissions.
- Pin risk occurs when a stock settles right at the strike price near expiration, leaving both sides unsure whether exercise or assignment will occur. Brokers set their own cutoff times and exercise policies, so investors should confirm those details in advance to avoid surprises.
Keep Learning:
Key Moments from Buying Options: Key Considerations for Investors
Key Moments from Selling Options: Key Considerations for Investors
Meet OIC Instructor
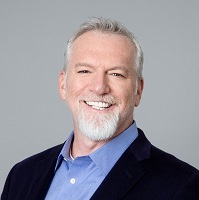
Mark Benzaquen
Mark, OIC instructor and Principal, Investor Education at OCC, brings 20+ years of experience with options in the Financial Services industry. Mark began his career in options with Stafford Trading, LLC in 1997 before transitioning to brokerage operations with MF Global in 2000. For more than a decade, Mark was the Lead Broker for his firm in the NDX/RUT trading pit, gaining special insight into customer order flow and trade execution.